Arizona Tile Contractor Insurance
See How We're Different:
or Call Us:(480) 526-3222
Running a tile contracting business in Arizona means working with fragile materials, sharp tools, and job sites that belong to someone else. A single cracked tile installation or a worker's knee injury can spiral into thousands of dollars in liability. Whether you're a one-person operation setting backsplashes in Scottsdale or a crew of fifteen handling
commercial flooring in Tucson, the right insurance coverage isn't optional: it's what keeps your business alive. This guide covers the essential policies Arizona tile contractors need, from general liability and completed operations to workers' comp, silica exposure risks, and equipment protection. Understanding these coverages helps you avoid the gaps that sink small contractors every year. The stakes are higher than most realize, too. Arizona's Registrar of Contractors (ROC) ties your license directly to your insurance status, and a
single missed premium payment can trigger automatic license suspension. That means an unpaid bill doesn't just leave you uninsured: it can legally stop your projects mid-tile.
Essential Insurance Requirements for Arizona Tile Professionals
Arizona regulates its contractors more tightly than many states. Any tile project where labor and materials exceed a $1,000 threshold requires a valid ROC license, and maintaining that license means keeping your insurance active without interruption. The ROC's system monitors coverage status in real time, so there's no grace period where you can quietly fix a lapse.
Beyond insurance, tile contractors must carry surety bonds ranging from $1,000 to $100,000 depending on your license classification and how much work you take on annually. These bonds protect your customers if you fail to complete a project or violate contract terms. They're separate from your liability coverage but equally mandatory.
Arizona also enforces an eight-year statute of repose for construction defects. That means you can be held liable for faulty tile work, cracked installations, or water damage caused by improper waterproofing for up to eight years after project completion. This long tail of liability makes completed operations coverage essential, not just a nice-to-have add-on.
One thing to keep in mind:
general contractors and commercial property managers in the Phoenix metro area increasingly require subcontractors to show proof of insurance before stepping on site. If you can't produce a certificate of insurance on demand, you're losing bids to competitors who can.
Core Coverages: General Liability and Workers' Comp
Two policies form the foundation of any tile contractor's insurance program: commercial general liability (CGL) and workers' compensation. Each covers a different type of risk, and Arizona law or market expectations make both practically mandatory.
General liability protects you when your work causes property damage or bodily injury to someone who isn't your employee. Think of a homeowner tripping over your tile saw cord, or a shower installation that leaks and destroys the subfloor below. Standard CGL policies for small Arizona tile contractors typically cost between $550 and $3,200 annually, though your exact premium depends on revenue, crew size, and claims history. The 2026 market is pushing those numbers higher: general liability pricing is trending upward by 5% to 8% this spring and summer due to rising claim costs and social inflation.
Workers' comp, on the other hand, covers your employees when they get hurt on the job. Arizona requires it for virtually all employers, and tile work carries real physical risks: sliced fingers, back injuries from lifting heavy stone, and repetitive stress on knees and wrists.
Protecting Against Third-Party Property Damage
Tile contractors face property damage claims more often than you might expect. The most common scenario isn't dramatic: it's a completed tile floor that starts cracking six months later because of improper substrate preparation. The homeowner calls a different contractor, gets a repair estimate, and sends you the bill.
Your CGL policy's completed operations coverage handles these post-project claims. Without it, you're personally responsible for repair costs, replacement materials, and potentially the damage your faulty work caused to surrounding areas. Water intrusion from a poorly waterproofed shower pan, for example, can lead to mold remediation bills that dwarf the original tile job.
Here's what that means for you: always confirm that your policy includes completed operations, and verify the coverage period extends long enough to match Arizona's eight-year statute of repose. Some basic policies cap completed operations at two or three years, which leaves you exposed.
Meeting Arizona Workers' Compensation Mandates
Arizona law requires workers' compensation for all employers, with very limited exceptions. If you hire even one part-time helper, you need a policy. The good news for 2026 is that Arizona approved a 6.7% reduction in voluntary workers' compensation loss costs, marking the twelfth straight year of rate decreases. That trend reflects improved workplace safety across the state's construction sector.
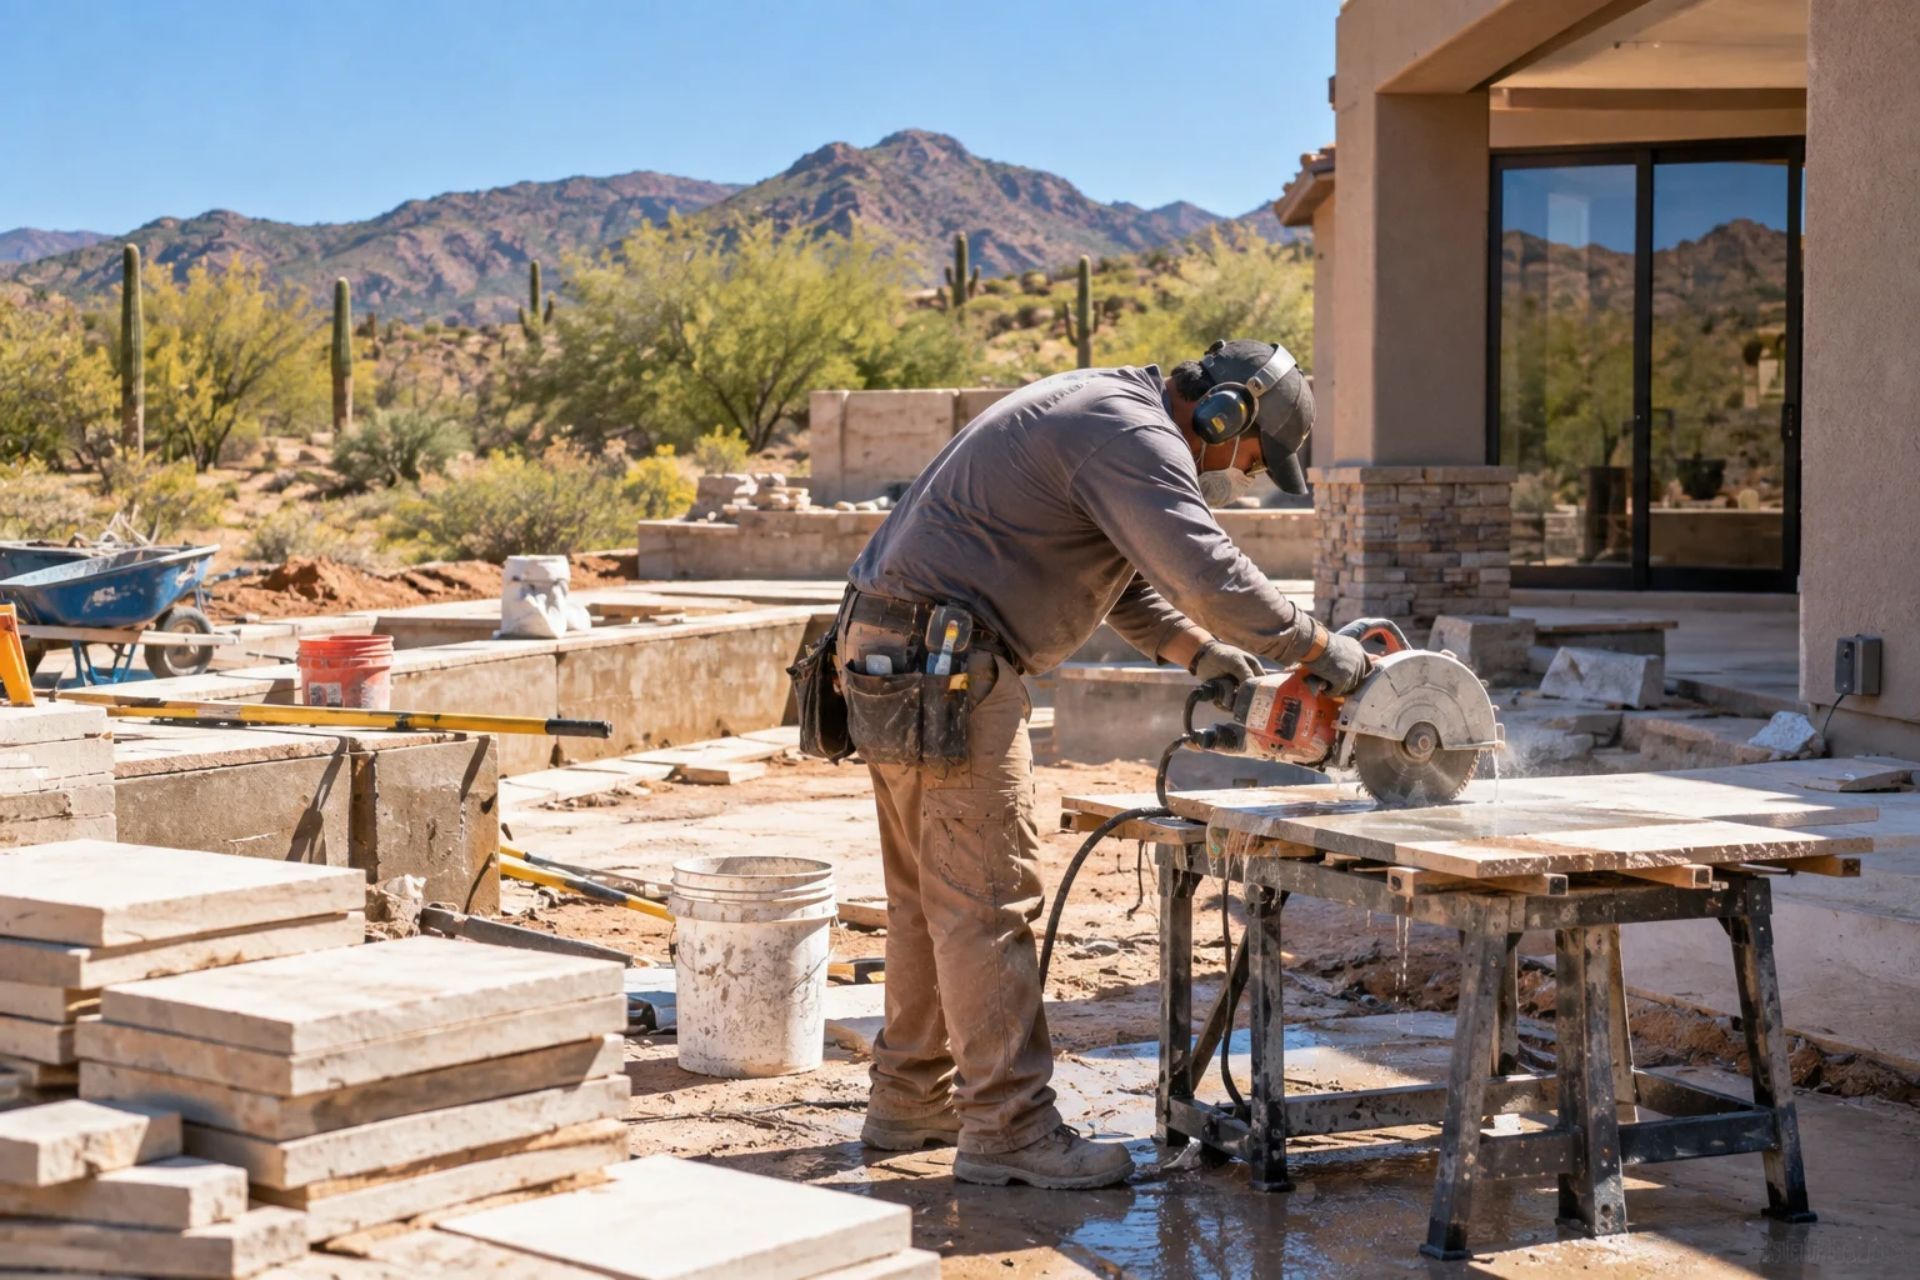
Tile work carries specific risks that affect your workers' comp classification and premiums. Silica dust exposure from cutting engineered stone and porcelain has become a major concern nationally, with some states moving toward restricting dry cutting entirely. Arizona hasn't enacted the same emergency restrictions as California, but OSHA's silica standards still apply. Providing wet-cutting equipment, proper respirators, and dust extraction systems doesn't just protect your crew: it can lower your experience modification rate and reduce premiums over time.
Sole proprietors can exempt themselves from workers' comp in Arizona, but doing so means your own medical bills after a job-site injury come out of pocket. Many experienced contractors carry the coverage anyway.
Protecting Your Assets: Tools, Equipment, and Vehicles
Your tile saws, mixing equipment, laser levels, and specialty hand tools represent a significant investment. A standard business property policy might cover items stored at a fixed location, but tile contractors move their equipment from job to job. That's where specialized coverage comes in.
If you own a work truck or van, commercial auto insurance is required. Personal auto policies exclude vehicles used for business purposes, so driving your truck to a job site with $8,000 worth of tools in the bed means neither the vehicle nor the cargo is properly covered under a personal policy.
Theft is a real concern in Arizona's construction market. Tools left in an unlocked trailer overnight at a residential job site are an easy target. Your commercial auto policy covers the vehicle itself, but the tools inside typically need separate protection.
Inland Marine Coverage for Mobile Equipment
Inland marine insurance is specifically designed for property that moves between locations. For tile contractors, this covers your wet saws, tile cutters, grout mixers, and other equipment while they're in transit, on a job site, or stored temporarily at a location that isn't your primary business address.
A typical inland marine policy lets you schedule high-value items individually and covers the rest under a blanket limit. If someone steals your $3,500 tile saw from a job site in Mesa, inland marine pays for the replacement. If your mixing equipment falls off a truck on the I-10, same thing.
The premiums are usually modest relative to the value they protect. Most small contractors pay a few hundred dollars annually for inland marine coverage, making it one of the better values in a contractor's insurance program.
Comparison: Basic Liability vs. Comprehensive Packages
Not every tile contractor needs the same level of coverage. Here's how a basic liability-only approach compares to a more complete package:
| Coverage Feature | Basic GL Only | Comprehensive Package |
|---|---|---|
| Third-party bodily injury | Included | Included |
| Third-party property damage | Included | Included |
| Completed operations | Often limited to 1-2 years | Matches statute of repose (8 years) |
| Workers' compensation | Not included | Included |
| Inland marine (tools/equipment) | Not included | Included |
| Commercial auto | Not included | Included |
| Excess/umbrella liability | Not included | Available |
| Typical annual cost range | $550 - $3,200 | See policy details |
The basic approach works if you're a sole proprietor doing small residential jobs with no employees. The moment you hire help, take on commercial work, or start bidding projects that require higher coverage limits, you'll need the comprehensive route. Many general contractors require $1 million per occurrence and $2 million aggregate before they'll let a sub on site.
Your insurance costs aren't random. Carriers weigh specific variables when pricing your policy, and understanding them gives you some control over what you pay.
Your annual revenue is the biggest factor for general liability. A contractor doing $150,000 in annual tile work will pay significantly less than one billing $750,000. Claims history matters too: even a single paid claim in the past three years can push your premium up 15% to 25%.
Crew size directly affects workers' comp costs. Each employee adds payroll to your premium calculation, and the classification code for tile work reflects the physical nature of the job. Your experience modification rate (EMR) either rewards or penalizes you based on your claims record compared to other contractors in the same class.
The type of work you do also plays a role. A contractor who exclusively installs ceramic floor tile in residential homes presents a different risk profile than one cutting and installing natural stone in commercial kitchens. Wet areas like showers and pools carry higher liability because water damage claims are expensive.
Geographic location within Arizona matters as well. Contractors working primarily in the Phoenix metro area may see slightly different rates than those in rural counties, partly because urban areas generate more claims and partly because property values affect damage estimates.
Frequently Asked Questions About Tile Insurance
Do I need insurance if I'm a sole proprietor with no employees? Yes. Arizona's ROC requires active liability insurance to maintain your contractor's license, regardless of whether you have employees. Workers' comp is the only coverage you can potentially skip as a sole proprietor.
What happens if my insurance lapses for even one day? The ROC can automatically suspend your license. You'd need to reinstate coverage and potentially pay penalties before resuming work. Any projects in progress would be legally halted.
Does my general liability policy cover cracked tiles I installed last year? Only if your policy includes completed operations coverage. A basic GL policy might not extend to defects discovered after the project wraps. Check your policy's completed operations period carefully.
How does silica exposure affect my insurance? Silica dust claims fall under workers' compensation if an employee develops silicosis or related lung conditions. Carriers may ask about your dust control practices during underwriting, and poor safety protocols can increase your premiums.
Can I bundle my policies to save money? Yes. A Business Owner's Policy (BOP) combines general liability with commercial property coverage at a discount. You can often add inland marine and other endorsements to a BOP for less than buying each policy separately.
What coverage limits should I carry?
Most commercial and residential general contractors require at least $1 million per occurrence and $2 million aggregate from their subs. If you're doing high-end residential work, consider an umbrella policy for additional protection.
Getting the right insurance for your Arizona tile contracting business isn't just about checking a box for the ROC. It's about matching your actual risk profile to coverages that will protect you when something goes wrong: a cracked shower pan, a worker's back injury, or a stolen trailer full of equipment.
Start by reviewing your current policies against the coverages outlined here. Pay special attention to your completed operations limits and whether they align with Arizona's eight-year statute of repose. If you're carrying only basic general liability, you likely have gaps that could cost you far more than the premium difference.
Get quotes from at least three carriers or brokers who specialize in contractor insurance. Generic business insurance agents often miss the nuances of tile work, like the difference between ceramic and natural stone risk classifications. A broker familiar with Arizona's construction market will know which carriers offer the best rates for your specific situation.
Don't wait for a claim to find out your coverage falls short. Review your policies annually, especially as your revenue grows or you add employees. The cost of proper coverage is always less than the cost of being uninsured when it matters.
About The Author:
Taylor Whatcott
As President of Wilde Wealth Insurance Services, I’m committed to providing trusted protection for both families and businesses across Arizona. Our independent team works with top-rated carriers to deliver tailored, comprehensive coverage—making insurance simple, accessible, and hassle-free.
Contact Us
Commercial Coverage Solutions
Protect Your Business with the Right Insurance
We offer customized insurance solutions to safeguard your business from financial risks. Our policies provide protection for property, employees, and liability concerns.
Commercial Property Insurance
Safeguards buildings, equipment, and inventory from damage or loss.
Professional Liability Insurance
Covers claims of negligence, errors, or omissions in services.
Cyber Liability Insurance
Protects against data breaches, cyberattacks, and online threats.
Who We Protect
Insurance Solutions for Your Industry
We specialize in providing tailored coverage for businesses in key industries. Our policies are designed to meet industry-specific risks and ensure complete protection.
Protection for Your Home & Assets
Reliable Coverage for Life’s Unexpected Moments
We provide personal insurance solutions designed to safeguard your home, vehicle, and financial well-being. Our policies ensure you and your loved ones are protected.
What Our Clients Say
Real Feedback. Real Confidence.
FAQs
Answers to Common Insurance Questions
How do I know which insurance coverage is right for me?
Choosing the right insurance depends on your personal or business needs. Our team evaluates your risks and recommends tailored coverage to protect what matters most.
We work with multiple carriers to provide different policy options. This allows you to compare benefits, limits, and pricing to make an informed choice.
If you’re unsure, we’ll walk you through the options step by step, ensuring you understand your coverage and feel confident in your decision.
Why should I choose an independent insurance agency like Wilde Wealth?
As an independent agency, we are not tied to a single insurance provider. This means we can compare multiple policies to find the best coverage at the best price.
Our goal is to advocate for you, ensuring you receive personalized service and expert advice tailored to your situation.
Unlike direct insurers, we offer ongoing support, helping you with claims, policy changes, and future coverage needs.
Can I bundle multiple insurance policies to save money?
Yes! Bundling policies like home and auto can lead to significant savings. Many carriers offer discounts for combining multiple coverages.
Bundling also simplifies policy management, with a single point of contact and streamlined renewals.
We help you explore bundling options to ensure you get the best value while maintaining the protection you need.
What factors affect my insurance rates?
Insurance rates are influenced by factors such as coverage limits, location, claims history, and risk exposure. Personal insurance may consider credit scores, driving history, and home value.
For businesses, factors like industry type, employee count, and annual revenue can impact pricing. Each carrier evaluates risk differently.
We shop multiple providers to find the best balance of coverage and cost, ensuring you don’t overpay while staying fully protected.
How does Wilde Wealth Insurance Services help business owners?
We provide customized business insurance solutions to protect against liability, property damage, employee-related risks, and cyber threats.
Our team works with a range of industries, including contractors, restaurants, and real estate professionals, to offer tailored policies.
From small startups to established enterprises, we help business owners minimize risks and keep operations running smoothly.
What happens if I need to file a claim?
Filing a claim is simple with our support. Contact us first, and we’ll guide you through the process, ensuring all necessary information is submitted correctly.
We work directly with your insurance carrier to expedite the claim, keeping you informed at every step.
Our team is here to advocate for you, making sure you receive a fair and timely resolution.
Latest Articles & Insights
Stay Informed with Expert Insurance Advice
We provide valuable insights to help you make informed insurance decisions. Explore our latest articles on coverage options, industry trends, and risk management tips.
Contact Us