Phoenix, AZ General Liability Insurance
See How We're Different:
or Call Us:(480) 526-3222
Running a business in Phoenix means dealing with heat, rapid growth, and a competitive market that doesn't slow down. It also means exposure to risks that can drain your bank account overnight: a customer slipping on your freshly mopped floor, a delivery gone wrong, or property damage at a job site. General liability insurance for Phoenix, AZ businesses isn't just a formality. It's the financial backstop that keeps a single bad day from becoming a permanent shutdown. Whether you're a solo contractor working in Scottsdale or running a retail shop near Roosevelt Row, understanding how this coverage works - and what it actually costs here - can save you from making expensive mistakes.
Understanding General Liability Insurance for Phoenix Businesses
General liability is the foundational policy that most Phoenix businesses buy first, and for good reason. It protects you from the financial fallout of accidents, injuries, and property damage tied to your daily operations. The median monthly cost for small businesses in the Phoenix metro area sits around $45, making it one of the more affordable forms of commercial coverage you can carry.
That said, price alone doesn't tell the full story. Your specific industry, location within the metro, and claims history all shape what you'll pay and what your policy actually covers. A food truck parked at First Friday events faces different exposures than a home-based consulting firm, and your policy should reflect that.
What Does General Liability Cover?
A standard general liability policy covers three core categories. Bodily injury pays for medical costs and legal fees if someone gets hurt on your premises or because of your operations. Property damage kicks in when your business activities cause harm to someone else's belongings or space. Advertising injury covers claims like slander, libel, or copyright infringement in your marketing materials.
Each of these categories has its own sublimit within your overall policy limit. A common structure is $1 million per occurrence with a $2 million aggregate, meaning the insurer will pay up to $1 million for any single claim and $2 million total during the policy period. For most small Phoenix businesses, this baseline is sufficient, though contractors and event-related businesses often need higher limits.
Common Risks for Local Business Owners
Phoenix's climate and construction boom create specific risk profiles. Landscapers and outdoor service providers deal with heat-related injuries on job sites year-round. The city's ongoing residential and commercial development means contractors face constant exposure to third-party property damage claims.
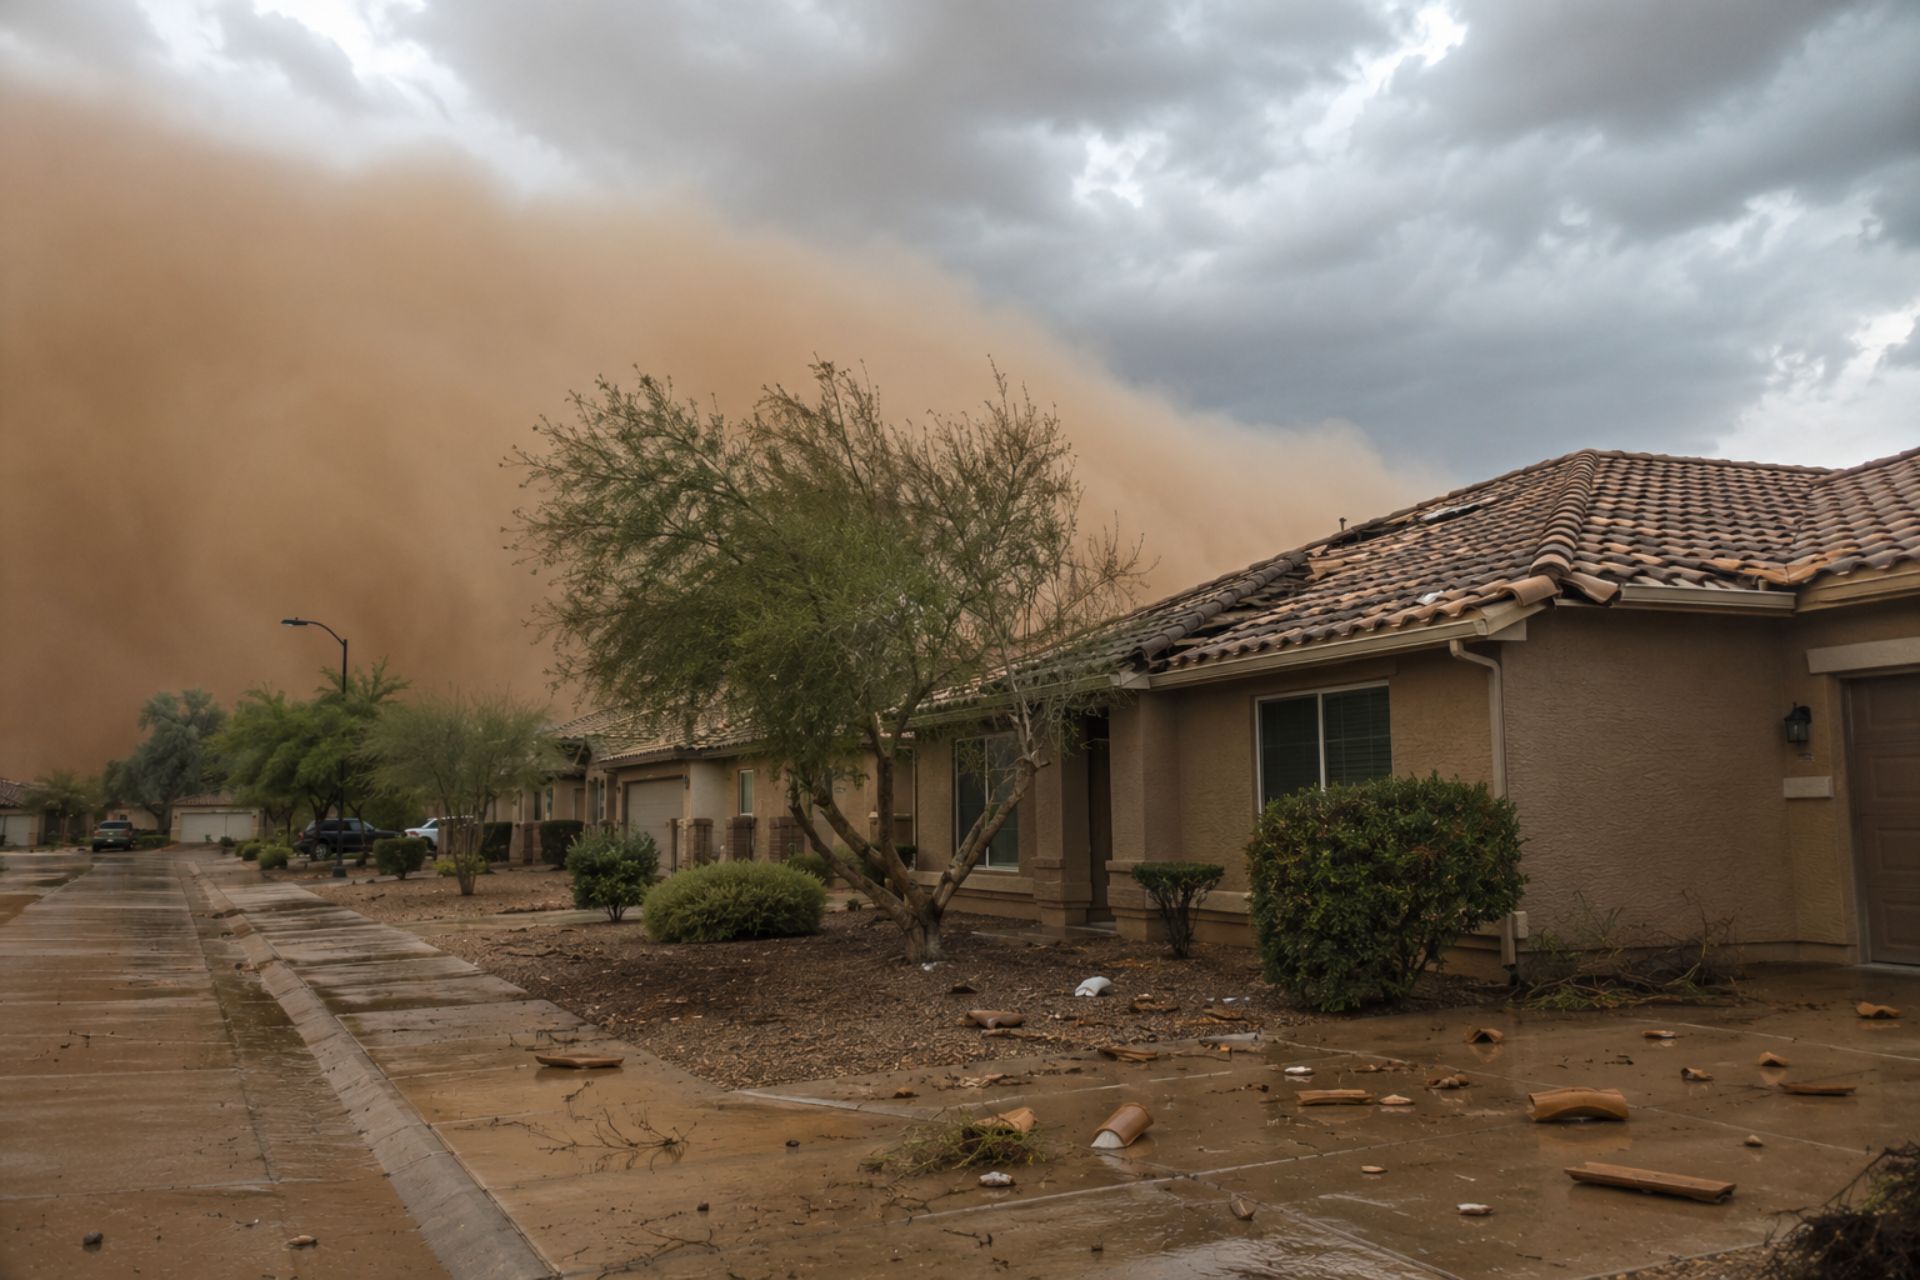
Retail and hospitality businesses in high-traffic areas like Tempe Marketplace or Old Town Scottsdale see elevated slip-and-fall risk, especially during monsoon season when wet floors become a liability magnet. Even home-based businesses aren't immune: if a client visits your home office and trips on a loose step, your homeowner's policy likely won't cover the claim. That gap is exactly what general liability fills.
Key Coverage Differences: General vs. Professional Liability
One of the most common mistakes Phoenix business owners make is assuming general liability covers everything. It doesn't. General liability handles physical incidents: someone gets hurt, something gets broken. Professional liability (also called errors and omissions, or E&O) covers mistakes in the services or advice you provide.
If you're an accountant who files a client's taxes incorrectly, or a marketing consultant whose campaign causes a client to lose revenue, those claims fall under professional liability. General liability wouldn't apply because no physical injury or property damage occurred. Many Phoenix businesses need both policies, and the 2026 commercial insurance market has seen growing demand for bundled coverage options that combine them.
Comparison Table: Choosing the Right Policy Type
| Feature | General Liability | Professional Liability (E&O) |
|---|---|---|
| Covers bodily injury | Yes | No |
| Covers property damage | Yes | No |
| Covers service errors | No | Yes |
| Covers advertising injury | Yes | Sometimes |
| Required by AZ contracts | Often | Industry-dependent |
| Typical monthly cost (Phoenix) | $30-$80 | $50-$150 |
| Best for | Contractors, retail, restaurants | Consultants, tech, financial services |
The right choice depends on your work. If you touch physical property or interact with the public in person, general liability is non-negotiable. If you provide advice, designs, or professional services, you need E&O as well. Many Phoenix businesses operating in both spaces carry a Business Owner's Policy (BOP) that bundles general liability with property coverage at a discounted rate.
Arizona Legal Requirements and Industry Standards
Arizona doesn't mandate general liability insurance for all businesses by state law. That surprises a lot of new business owners. The state does require workers' compensation if you have employees, but general liability remains technically optional from a regulatory standpoint.
Here's the catch: "optional" doesn't mean unnecessary. Contracts, leases, and licensing boards throughout Maricopa County frequently require proof of general liability before you can start work or sign an agreement. In practice, operating without it in Phoenix is nearly impossible if you want to grow beyond a one-person operation.
State-Specific Regulations for Contractors
Arizona's Registrar of Contractors (ROC) requires licensed contractors to carry liability coverage. The minimum depends on your license classification, but most residential and commercial contractors need at least $100,000 to $300,000 in coverage. Specialty trades like electrical, plumbing, and HVAC often face higher requirements.
Contractor insurance costs in Arizona vary significantly based on trade and project scope. A general contractor running crews on large commercial builds will pay substantially more than a solo handyman doing residential repairs. The ROC audits compliance, and operating without adequate coverage can result in license suspension - a risk no contractor can afford in Phoenix's booming construction market.
Why Phoenix Landlords and Venues Require Coverage
If you lease commercial space in Phoenix, your landlord almost certainly requires you to carry general liability and name them as an additional insured on your policy. This protects the property owner from lawsuits that originate from your business activities within their building.
Event venues across the Valley follow the same pattern. Booking space at the Phoenix Convention Center, a Scottsdale resort, or even a local community center typically requires a Certificate of Insurance (COI) showing active general liability coverage. The minimum they'll accept is usually $1 million per occurrence. Some venues in high-end areas require $2 million or more, particularly for events involving alcohol or large crowds.
Your premium isn't pulled from thin air. Insurers use several variables to calculate what you'll pay, and understanding them gives you more control over your costs.
Industry classification is the biggest driver. A roofing contractor will always pay more than an accounting firm because the physical risk exposure is dramatically different. Your annual revenue matters too: higher revenue generally means more customer interactions and greater exposure, which pushes premiums up.
Claims history plays a significant role. If you've filed multiple claims in the past three to five years, expect to pay more. Your business location within Phoenix also factors in - a storefront in a high-traffic shopping district carries more foot traffic risk than a warehouse in an industrial park near Sky Harbor. The property and casualty market in 2026 has shown some rate moderation compared to prior years, which is good news for Phoenix businesses shopping for new policies.
One thing to keep in mind: your deductible directly affects your premium. Choosing a higher deductible lowers your monthly cost but increases your out-of-pocket expense when a claim occurs. For businesses with strong cash reserves, a higher deductible can be a smart trade-off.
Common Questions About Phoenix Liability Insurance
Do I need general liability if I work from home? Yes, if clients visit your home or you perform services at other locations. Your homeowner's policy excludes business-related claims, leaving you exposed without a separate commercial policy.
How fast can I get a policy? Most insurers can bind coverage within 24 to 48 hours. Some online platforms issue same-day policies for low-risk businesses. You'll receive your COI immediately after binding.
Does general liability cover employee injuries? No. Employee injuries fall under workers' compensation insurance, which Arizona requires for businesses with one or more employees. General liability only covers third parties - customers, vendors, and bystanders.
Can I bundle general liability with other coverage? Absolutely. A Business Owner's Policy (BOP) combines general liability with commercial property insurance, usually at a 10-20% discount compared to buying them separately. It's the most popular option for small Phoenix businesses.
What happens if I'm sued and don't have coverage? You pay everything out of pocket: legal defense, settlements, court costs. Even a minor slip-and-fall claim can generate $20,000 to $50,000 in expenses. A lawsuit without insurance can bankrupt a small business.
Does my policy cover me across Arizona, or just Phoenix? Most general liability policies provide coverage throughout the state and even nationally. Your "territory" is defined in the policy declarations page, but standard commercial general liability forms typically cover operations anywhere in the U.S.
How do AI and technology trends affect my coverage needs?
Businesses using AI tools for customer interactions or data processing face
emerging legal questions around liability that traditional policies may not fully address. If your business relies heavily on technology, discuss potential coverage gaps with your agent.
Making the Right Choice for Your Business
Picking the right liability insurance isn't about finding the cheapest premium. It's about matching your coverage to your actual risk profile. A Phoenix restaurant with outdoor patio seating, delivery drivers, and a liquor license has a completely different exposure than a graphic design studio operating out of a co-working space downtown.
Start by listing every way your business interacts with the public, other businesses, and physical spaces. Each interaction point is a potential claim. Then work with an agent or broker who understands the Phoenix market - someone who knows that monsoon season changes your risk profile, that Maricopa County permitting requirements affect contractor coverage, and that insurance trends in 2026 are shifting how policies are structured.
How to Determine Your Coverage Limits
The standard $1 million per occurrence and $2 million aggregate works for most small businesses, but don't assume it's enough for yours. Look at your contracts first: many commercial clients and landlords specify minimum coverage amounts, and falling short means losing the deal.
Consider your assets. If your business owns significant equipment, vehicles, or inventory, a lawsuit judgment could target those assets. Your coverage limit should be high enough to protect what you've built. For businesses with substantial exposure, an umbrella policy adds an extra layer above your general liability limits at a relatively low cost - often just a few hundred dollars per year for an additional $1 million in protection.
Steps to Get a Quote and Start Coverage
Getting covered doesn't need to be complicated. Here's a straightforward process:
- Gather your business details: EIN, annual revenue, number of employees, years in operation, and your specific industry classification.
- Document your lease or contract requirements so you know the minimum coverage limits you need to meet.
- Request quotes from at least three sources: an independent agent, a direct carrier, and an online platform. Comparing multiple options ensures you're not overpaying.
- Review each quote's exclusions carefully. The cheapest policy might exclude the exact scenario most likely to affect your business.
- Once you select a policy, bind coverage and request your COI immediately. Most landlords and clients need this document before you can start work.
The whole process typically takes less than a week from first quote to active coverage. For straightforward businesses, you can often complete everything in a single day.
Phoenix is a city where opportunity and risk grow side by side. The businesses that thrive here aren't the ones that avoid risk entirely - they're the ones that protect themselves intelligently. Getting the right general liability coverage in place is one of the simplest, most cost-effective steps you can take to keep your Phoenix business moving forward. Don't wait for a claim to find out what you should have done differently. Get your quotes, compare your options, and lock in coverage before your next customer walks through the door.
About The Author:
Taylor Whatcott
As President of Wilde Wealth Insurance Services, I’m committed to providing trusted protection for both families and businesses across Arizona. Our independent team works with top-rated carriers to deliver tailored, comprehensive coverage—making insurance simple, accessible, and hassle-free.
Contact Us
Commercial Coverage Solutions
Protect Your Business with the Right Insurance
We offer customized insurance solutions to safeguard your business from financial risks. Our policies provide protection for property, employees, and liability concerns.
Commercial Property Insurance
Safeguards buildings, equipment, and inventory from damage or loss.
Professional Liability Insurance
Covers claims of negligence, errors, or omissions in services.
Cyber Liability Insurance
Protects against data breaches, cyberattacks, and online threats.
Who We Protect
Insurance Solutions for Your Industry
We specialize in providing tailored coverage for businesses in key industries. Our policies are designed to meet industry-specific risks and ensure complete protection.
Protection for Your Home & Assets
Reliable Coverage for Life’s Unexpected Moments
We provide personal insurance solutions designed to safeguard your home, vehicle, and financial well-being. Our policies ensure you and your loved ones are protected.
What Our Clients Say
Real Feedback. Real Confidence.
FAQs
Answers to Common Insurance Questions
How do I know which insurance coverage is right for me?
Choosing the right insurance depends on your personal or business needs. Our team evaluates your risks and recommends tailored coverage to protect what matters most.
We work with multiple carriers to provide different policy options. This allows you to compare benefits, limits, and pricing to make an informed choice.
If you’re unsure, we’ll walk you through the options step by step, ensuring you understand your coverage and feel confident in your decision.
Why should I choose an independent insurance agency like Wilde Wealth?
As an independent agency, we are not tied to a single insurance provider. This means we can compare multiple policies to find the best coverage at the best price.
Our goal is to advocate for you, ensuring you receive personalized service and expert advice tailored to your situation.
Unlike direct insurers, we offer ongoing support, helping you with claims, policy changes, and future coverage needs.
Can I bundle multiple insurance policies to save money?
Yes! Bundling policies like home and auto can lead to significant savings. Many carriers offer discounts for combining multiple coverages.
Bundling also simplifies policy management, with a single point of contact and streamlined renewals.
We help you explore bundling options to ensure you get the best value while maintaining the protection you need.
What factors affect my insurance rates?
Insurance rates are influenced by factors such as coverage limits, location, claims history, and risk exposure. Personal insurance may consider credit scores, driving history, and home value.
For businesses, factors like industry type, employee count, and annual revenue can impact pricing. Each carrier evaluates risk differently.
We shop multiple providers to find the best balance of coverage and cost, ensuring you don’t overpay while staying fully protected.
How does Wilde Wealth Insurance Services help business owners?
We provide customized business insurance solutions to protect against liability, property damage, employee-related risks, and cyber threats.
Our team works with a range of industries, including contractors, restaurants, and real estate professionals, to offer tailored policies.
From small startups to established enterprises, we help business owners minimize risks and keep operations running smoothly.
What happens if I need to file a claim?
Filing a claim is simple with our support. Contact us first, and we’ll guide you through the process, ensuring all necessary information is submitted correctly.
We work directly with your insurance carrier to expedite the claim, keeping you informed at every step.
Our team is here to advocate for you, making sure you receive a fair and timely resolution.
Latest Articles & Insights
Stay Informed with Expert Insurance Advice
We provide valuable insights to help you make informed insurance decisions. Explore our latest articles on coverage options, industry trends, and risk management tips.
Contact Us